How Much Should First-Time Homebuyers in Florida Really Save?
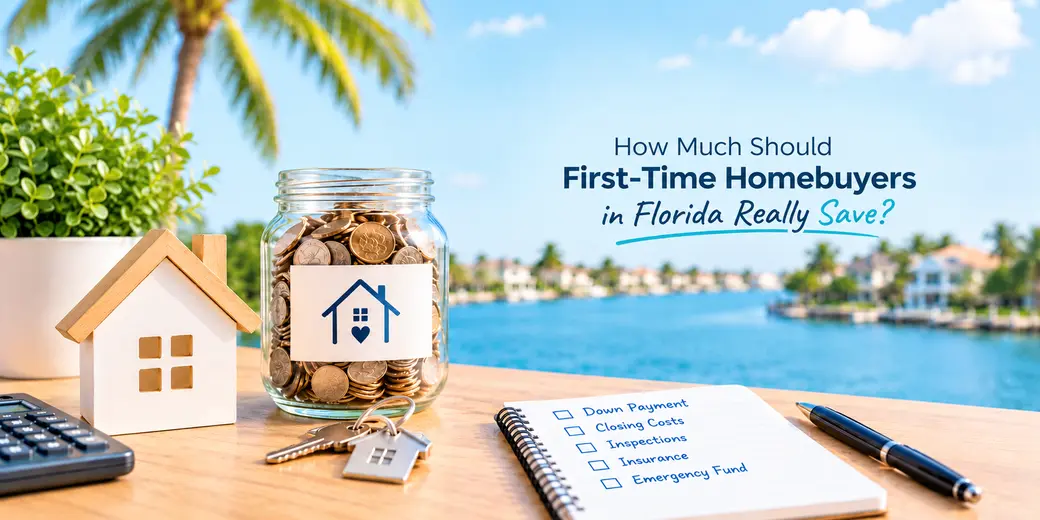
How Much Should First-Time Homebuyers in Florida Really Save?
Buying your first home in Florida is an exciting milestone, but the down payment is only one part of the overall cost. From earnest money and inspections to closing expenses and ongoing homeownership costs, understanding what to expect can help you plan confidently and avoid last-minute financial surprises.
1. Earnest Money Deposit: Show Your Commitment
Once your offer is accepted, you may be required to submit an earnest money deposit. This deposit demonstrates your commitment to the purchase and is typically held in escrow according to the terms of your contract.
What to keep in mind:
-
The amount depends on the purchase agreement and local market practices.
-
The contract specifies when the deposit must be paid.
-
The deposit is generally credited toward your purchase at closing, subject to the contract terms.
-
Understand the conditions under which the deposit may be refundable or at risk.
2. Down Payment: Know Your Financing Options
Your down payment will depend on the mortgage program, purchase price, credit profile, and lender requirements. Some loan programs allow eligible buyers to purchase a home with a relatively small down payment, while others may require more.
Before deciding on your down payment:
-
Explore different mortgage programs with a qualified lender.
-
Ask whether you qualify for first-time homebuyer assistance.
-
Compare the down payment requirements and monthly payments of available loan options.
-
Keep enough savings available for closing costs and unexpected expenses.
Remember, putting more money down is not always the best choice if it leaves you without sufficient savings after closing.
3. Home Inspections and Appraisal: Evaluate Before You Buy
Before finalizing your purchase, you may need to pay for a home inspection and lender-required appraisal. These services help you evaluate the property's condition and support the financing process.
Potential expenses include:
-
General home inspection.
-
Pest, roof, plumbing, or other specialized inspections, when appropriate.
-
Wind mitigation or four-point inspections, when needed for insurance purposes.
-
Lender-required property appraisal.
The exact expenses depend on the property and the services required. Budget for these costs early so you can make informed decisions during the due diligence period.
4. Closing Costs: Plan Beyond the Purchase Price
Closing costs can add a significant amount to your upfront expenses. Depending on your transaction, these may include lender fees, title and settlement charges, recording fees, prepaid property taxes, homeowners insurance, and escrow deposits.
In Florida, pay particular attention to:
-
Homeowners insurance premiums and coverage requirements.
-
Property taxes and applicable tax prorations.
-
Flood insurance, if required or appropriate for the property.
-
Title-related charges and other settlement expenses.
-
Condominium or homeowners association fees and application charges, if applicable.
Ask your lender for a Loan Estimate early in the process and review your Closing Disclosure before closing. Your actual costs will depend on the property, loan, contract, and applicable local requirements.
5. Moving and Initial Homeownership Expenses
Your financial planning should not end when you receive the keys. Moving into a new home can bring additional expenses that are easy to overlook.
Consider setting aside funds for:
-
Moving services and transportation.
-
Utility connection fees and deposits.
-
Essential furniture and household appliances.
-
Minor repairs, maintenance, or immediate improvements.
-
HOA or condominium association requirements, where applicable.
Planning for these expenses can help you settle into your new home without putting unnecessary pressure on your budget.
6. Emergency Savings: Protect Your Financial Comfort
Unexpected repairs and ownership expenses can arise at any time. Maintaining an emergency fund helps you manage these costs without relying entirely on credit cards or loans.
Build a financial cushion for:
-
Appliance or air-conditioning repairs.
-
Plumbing and electrical issues.
-
Insurance deductibles.
-
Routine maintenance and unexpected property expenses.
-
Temporary changes in income or other financial obligations.
Your ideal reserve will depend on your income, existing savings, monthly expenses, and the condition of the home. Avoid committing every available dollar to the purchase itself.
How Much Should You Have Saved Before Buying?
There is no single savings target that works for every first-time homebuyer. Your total upfront budget will depend on your purchase price, financing, inspections, insurance, closing costs, and moving expenses.
Before making an offer, consider these essential steps:
-
Speak with a lender: Understand your borrowing capacity, estimated monthly payment, and available assistance programs.
-
Request a realistic cost estimate: Review anticipated closing costs, prepaid expenses, and cash needed to close.
-
Explore insurance early: Obtain preliminary quotes and confirm any property-specific coverage requirements.
-
Review the property carefully: Consider its condition, association fees, maintenance needs, and other ongoing expenses.
-
Protect your savings: Keep an emergency reserve separate from the funds allocated to purchasing the home.
A little preparation now can help you move forward with greater confidence and fewer financial surprises.
Let’s Make Your Florida Homebuying Journey Easier
Buying a home is about more than finding the right property. It is about making a decision that supports your lifestyle, financial goals, and long-term peace of mind.
Whether you are purchasing your first home, planning a seasonal stay, or relocating to South Florida or Southwest Florida, I am here to help you navigate the real estate process and understand the next steps.
Maylene Gonzalez, P.A.
Florida Real Estate Professional
Serving Southwest Florida and South Florida
www.maylenegonzalez.com
Categories
Recent Posts